
Powered by Google TranslateTranslate
Markets
CATCaterpillar$510.45-5.01%•
DEDeere & Co.$609.25-2.50%•
CNHCNH Industrial$10.74-2.98%•
AGCOAGCO Corp.$100.93-1.91%•
URIUnited Rentals$973.43-8.13%•
ALTGAlta Equipment$4.33-8.46%•
TTCToro Company$100.82-1.70%•
HRIHerc Holdings$133.55-11.54%•
MGRCMcGrath RentCorp$113.45-6.38%•
MTWManitowoc$20.31-5.58%•
CATCaterpillar$510.45-5.01%•
DEDeere & Co.$609.25-2.50%•
CNHCNH Industrial$10.74-2.98%•
AGCOAGCO Corp.$100.93-1.91%•
URIUnited Rentals$973.43-8.13%•
ALTGAlta Equipment$4.33-8.46%•
TTCToro Company$100.82-1.70%•
HRIHerc Holdings$133.55-11.54%•
MGRCMcGrath RentCorp$113.45-6.38%•
MTWManitowoc$20.31-5.58%•

AGCO’s Q2 Pause Tests the Durability of Its Precision-Agriculture Strategy

Jon RossiJon RossiFounder & Editor-in-Chief September 30, 2026 3 min read

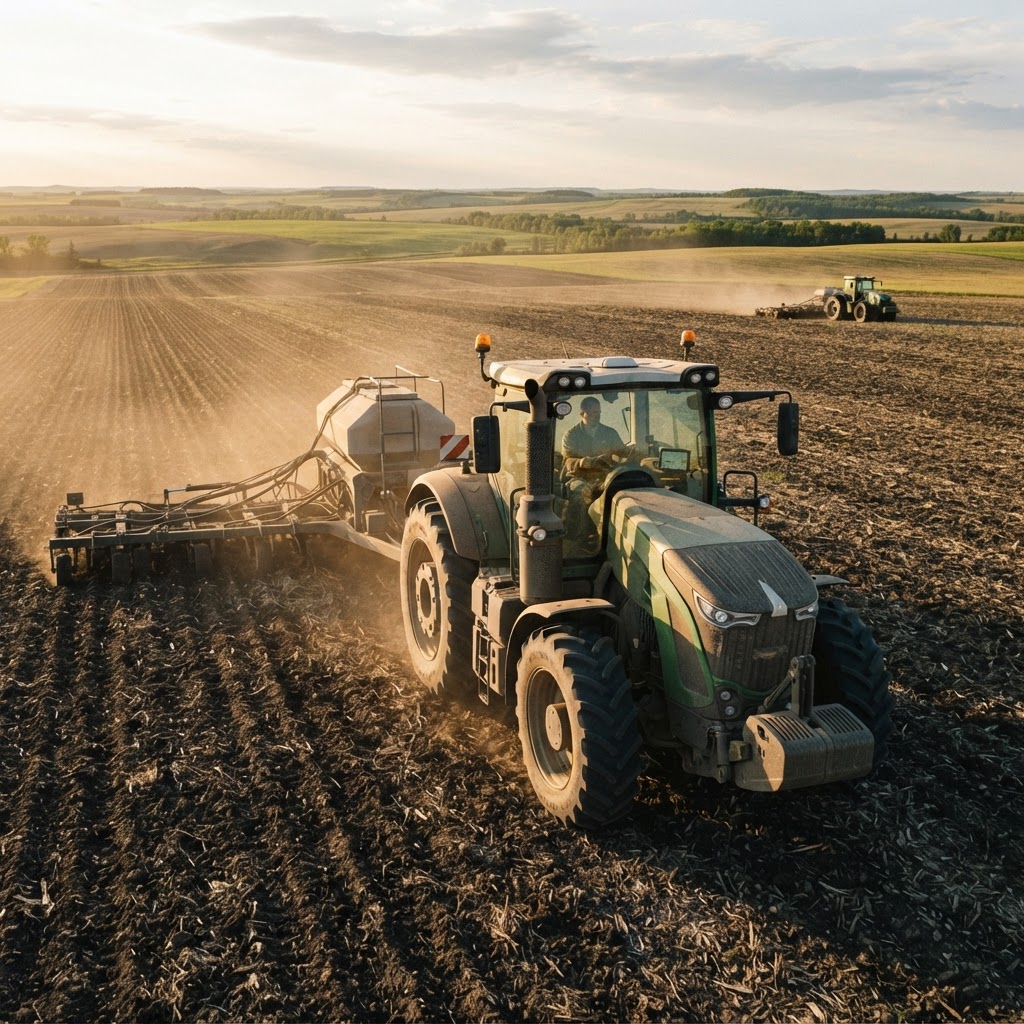
AGCO’s second-quarter sales eased 1.0% year over year to $2.6 billion after a stronger first quarter. The results point to a market that is uneven, while the company continues to build around Fendt, Massey Ferguson, and PTx precision technologies.

AGCO’s Q2 Pause Tests the Durability of Its Precision-Agriculture Strategy

AGCO’s second-quarter 2026 results show a manufacturer holding near last year’s sales level, but not advancing at the pace established in the opening quarter. Net sales reached $2.6 billion, down 1.0% from the second quarter of 2025, according to the company’s July 30 newsroom release. That followed first-quarter sales of $2.3 billion, up 14.3% year over year.

DIG Analysis — 2026-09-30: The central signal is not a collapse in demand. It is a widening gap between early-year momentum and second-quarter execution. AGCO is operating in a market where equipment replacement, farm income, inventory levels, and regional demand are moving at different speeds. Its long-term precision-agriculture strategy remains intact, but the near-term test is converting that strategy into measurable sales and margin resilience across distinct brands and customer segments.

Q2 moderates after a strong start

The sequential story matters. A 14.3% first-quarter sales increase created a high comparison point for the rest of the year. By the second quarter, AGCO had reached $2.6 billion in revenue, only slightly below the prior-year period. That result suggests the company retained substantial commercial volume even as the pace of growth cooled.

For equipment manufacturers, a flat or modestly lower quarter can reflect several conditions at once: delayed purchases, cautious farm balance sheets, uneven regional replacement cycles, or tighter dealer inventories. The published headline does not identify one single cause, so the more useful reading is operational. AGCO must manage production, channel stock, and product mix without assuming that first-quarter demand patterns will repeat.

The brand structure adds another layer. Fendt serves a premium segment with higher technology content and pricing expectations. Massey Ferguson addresses a broader global customer base, while PTx extends AGCO’s precision-agriculture position through guidance, autonomy, and data-linked farm-management tools. Performance across those businesses will not move in lockstep, making mix and regional execution as important as total sales.

“The second-quarter result reinforces the need to separate short-term market timing from AGCO’s longer-term product and technology direction.”

Precision agriculture remains the strategic anchor

AGCO continues to frame precision agriculture and autonomous solutions as core to its future across Fendt, Massey Ferguson, and PTx. That approach gives the company a way to compete beyond horsepower and attachment capacity. It also creates a demanding commercial requirement: technology must solve specific farm problems, integrate with existing equipment, and produce a credible return for customers facing uncertain commodity economics.

PTx is particularly important in that equation because precision products can influence both new-machine purchases and upgrades to existing fleets. Guidance, machine control, autonomy, and data services can create additional revenue opportunities, but adoption depends on dealer capability, interoperability, local agronomic support, and financing. A strong technology narrative will not substitute for reliable implementation in the field.

Fendt’s premium positioning can support advanced feature adoption where customers prioritize productivity and automation. Massey Ferguson provides broader distribution and market reach, giving AGCO a larger surface for introducing selected precision capabilities. The strategic challenge is maintaining clear brand roles while avoiding technology fragmentation for customers who operate mixed fleets.

What the next results must clarify

AGCO’s next disclosures will be judged against three questions. First, did the second-quarter moderation come from temporary timing or a broader slowdown in equipment demand? Second, is the company protecting profitability through product mix and disciplined production? Third, are precision and autonomous offerings moving from strategic promise into recurring customer adoption?

The answers will shape how the market views the 2026 trajectory. A modest year-over-year decline is manageable if AGCO is preserving channel health and building technology attachment rates. It becomes more concerning if softer demand is paired with rising inventory, weaker pricing, or delayed customer acceptance of new systems.

For now, the verified data supports a measured conclusion. AGCO remains commercially large, strategically focused, and exposed to a cyclical market that is not delivering uniform growth. The second quarter did not overturn the company’s direction, but it did raise the execution bar for the remainder of 2026.

Who This Affects

OEM Impact

AGCO product leaders, regional presidents, and OEM channel managers must reconcile strong first-quarter momentum with a nearly flat second quarter. Second-order pressure will fall on production planners and precision-product teams to manage inventory, protect mix, and prove that PTx features can lift revenue without slowing dealer adoption.

Dealer Impact

Dealer principals and branch sales managers should expect more scrutiny of inventory turns, demo-machine utilization, and attachment rates for guidance and autonomous features. If farm customers remain cautious, dealers may need to emphasize retrofit economics and service revenue while avoiding excess stock in premium units.

Contractor Impact

Custom operators and agricultural contractors may see more targeted selling around uptime, machine control, and labor-saving features rather than broad fleet expansion. Their purchasing decisions will influence reference accounts and regional adoption, especially where autonomous or precision tools can reduce operator shortages.

Startup Impact

Series A founders building autonomy, farm software, sensing, or retrofit systems face a more demanding OEM market, with buyers likely to prioritize integrations that support near-term customer payback. AGCO’s continued PTx focus may increase partnership opportunities while raising certification, interoperability, and channel-access hurdles.

Dealmaker Impact

PE dealmakers and corporate development teams should treat AGCO’s results as evidence of uneven equipment-cycle conditions, not a simple sector-wide growth signal. Valuation work for dealerships, precision-tech suppliers, and specialty manufacturers should stress-test inventory, replacement timing, OEM concentration, and recurring software revenue assumptions.

Back to News
AGCOFendtMassey FergusonPTxprecision agricultureautonomyOEM results