
Markets
CATCaterpillar$510.45-5.01%•
DEDeere & Co.$609.25-2.50%•
CNHCNH Industrial$10.74-2.98%•
AGCOAGCO Corp.$100.93-1.91%•
URIUnited Rentals$973.43-8.13%•
ALTGAlta Equipment$4.33-8.46%•
TTCToro Company$100.82-1.70%•
HRIHerc Holdings$133.55-11.54%•
MGRCMcGrath RentCorp$113.45-6.38%•
MTWManitowoc$20.31-5.58%•
CATCaterpillar$510.45-5.01%•
DEDeere & Co.$609.25-2.50%•
CNHCNH Industrial$10.74-2.98%•
AGCOAGCO Corp.$100.93-1.91%•
URIUnited Rentals$973.43-8.13%•
ALTGAlta Equipment$4.33-8.46%•
TTCToro Company$100.82-1.70%•
HRIHerc Holdings$133.55-11.54%•
MGRCMcGrath RentCorp$113.45-6.38%•
MTWManitowoc$20.31-5.58%•
Back to Newsmarket-intelligence

Typhon’s Direct-To-Contractor Play: Four Compact Machines Hit U.S. Online Storefront

Jon RossiJon RossiFounder & Editor-in-Chief August 8, 2026 3 min read

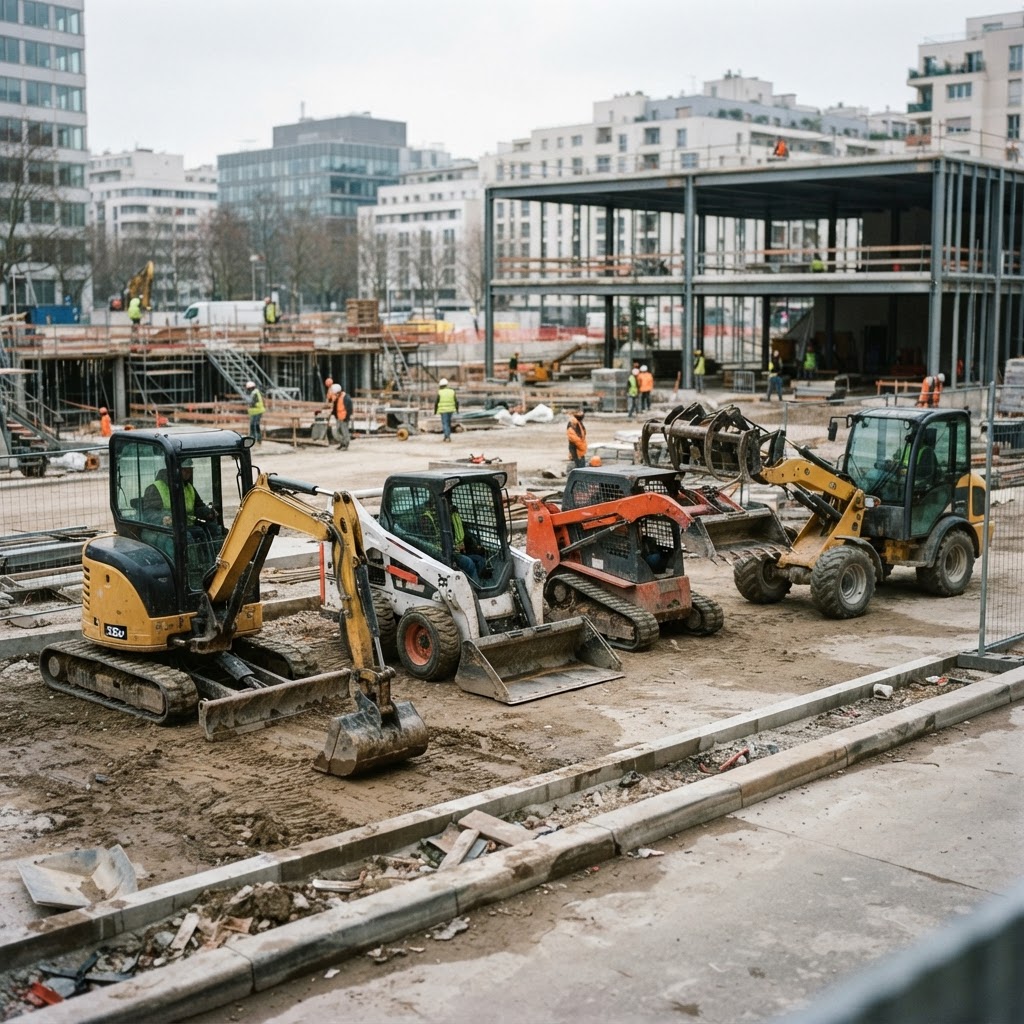
Singapore OEM Typhon launched four compact units for the U.S. market and opened direct online purchasing, shifting its distribution approach and testing dealer channel norms. Equipment World confirmed the rollout of a mini excavator, skid steer, mini track loader, and telescopic wheel loader.

Typhon’s Direct-To-Contractor Play: Four Compact Machines Hit U.S. Online Storefront

Typhon, a Singapore-based equipment manufacturer, has formally entered the U.S. compact equipment market with four new machines and a direct online purchase option aimed at contractors. The lineup includes a mini excavator, a skid steer, a mini track loader, and a telescopic wheel loader. Equipment World reported the launch and the new online sales pathway, which signals a deliberate change in how Typhon intends to reach U.S. buyers.

DIG Analysis — 2026-08-08: Typhon is executing a low-friction market entry by pairing compact product introductions with direct-to-customer eCommerce. That combination reduces initial channel costs and accelerates unit placement, but it will pressure local dealers and raise questions about aftersales support, parts logistics, and warranty handling.

What Typhon launched and how it differs from the incumbents

The machines themselves align with the established size and capability classes familiar to contractors: subcompact excavator class, loader class under six tons, and compact track and wheel platforms for tight urban sites. The product specs reported by Equipment World emphasize compact dimensions, payload and lift capacity competitive with comparable models from established brands, and a focus on ease of transport and operation.

The immediate differentiator is sales channel. Rather than building an exclusive dealer network first, Typhon has chosen to list these models for direct online sale to end users in the U.S. That approach lets the company collect buyer data, control pricing and promotions, and iterate quickly on entry-level support packages. It also shifts early service burdens onto Typhon and any third parties it engages for parts distribution and field service.

Why the distribution change matters to market dynamics

Dealers and OEM channel managers should treat this move as a selective market incursion rather than a broad channel revolt. Typhon is targeting compact segments where purchase cycles are shorter, replacement frequency is higher, and buyers are more willing to transact online for lower price points. For contractors and fleet operators, the ability to compare models and buy directly online reduces friction for small to medium purchases and can shave weeks from traditional procurement timelines.

  • Short term impact: quicker unit placement and lower customer acquisition cost for Typhon.
  • Mid term risk: dealer-distributed brands may face retail margin pressure and must defend value through service, financing, and local availability of parts.
  • Service challenge: Typhon will need to either build regional parts hubs or partner with independent service providers to meet downtime expectations.
"Selling compact machines online lets Typhon test price sensitivity and service models in the U.S. without committing to a full dealer network." — Equipment World

Typhon’s strategy mirrors digital-first moves seen in adjacent heavy equipment categories, but execution will hinge on aftersales reliability. Contractors value uptime and local support. If Typhon can match or exceed the responsiveness of local dealers through logistics and contracted service networks, the company can convert early adopters into repeat buyers. If not, the lack of native dealer support will limit adoption to owners willing to manage parts and repairs themselves.

Short run outcomes and measurable signals to watch

Over the next 12 months watch for three measurable signals. First, unit sales velocity posted through Typhon’s online channel versus comparable compact offerings. Second, warranty claim rates and response times that reveal the robustness of Typhon’s support model. Third, dealer pushback in the form of promotional adjustments or localized service offerings intended to highlight dealer strength.

Typhon’s U.S. entry is pragmatic. The company launched specific, easy-to-ship models and paired them with a sales channel that reduces early overhead. The task ahead is operational. The brand must prove it can support machines in the field and keep downtime low. That will determine whether this is a one-off market test or the opening chapter of a broader channel strategy in North America.

Who This Affects

OEM Impact

OEMs face direct online competition in compact classes where price and convenience matter most. Product managers and channel strategists must quantify the threat by tracking Typhon unit sales, online pricing patterns, and warranty claim behavior to decide if they need faster digital offers or reinforced service commitments.

Dealer Impact

Dealer principals and regional general managers will see pressure on margins in entry-level compact segments and may lose transactional sales to Typhon s online storefront. Expect dealers to emphasize service contracts, local parts availability, and financing options to differentiate and protect recurring revenue.

Contractor Impact

Fleet managers and small business owners gain faster access to compact machines and potentially lower upfront costs, but they take on greater risk for service and parts logistics if Typhon s local support is limited. Contractors should demand clear warranty terms and confirm local service arrangements before purchasing online.

Startup Impact

Series A and growth-stage startups in equipment software, parts logistics, and field service have a new potential customer in Typhon and a market opportunity to provide third-party support networks. Companies offering predictive maintenance, parts-as-a-service, and on-demand technician marketplaces could form partnerships to fill Typhon s aftersales gaps.

Dealmaker Impact

Private equity dealmakers and corporate development leads should track Typhon as a candidate for strategic partnership or tuck-in acquisition by established distributors seeking digital reach. Early transactional data and warranty performance will signal whether Typhon is a viable acquisition target or a source of channel disruption to hedge against.

Back to News
Typhoncompact-equipmentdirect-salesdistributionmini-excavatorskid-steerU.S.-market